 how-to
Easy Savings Growth Calculator 2026: How to Use It
Last Updated: November 1, 2026
Quick Summary
A savings growth calculator takes your starting balance, regular deposits, interest rate, and time horizon, then projects what your savings could be worth at the end. Capital Rewards offers free, real-time calculators that show the math without an account or a spreadsheet. The output separates total contributions from interest earned, which is the split that tells you whether your plan is doing real work.
- Five inputs drive every projection: starting balance, contributions, rate, compounding frequency, and time horizon.
- Enter the rate exactly as the field label asks, or a 4% rate typed as 0.04 understates growth by a factor of 100.
- In the worked example, $14,000 contributed over 5 years grows to roughly $15,695.80.
- A savings goal calculator works backward from your goal amount and target date to return the deposit you need.
- Check fees, taxes, and variable rates before you trust any projected balance.
Table of Contents
- How a Savings Growth Calculator Turns Deposits Into Projections
- How to Calculate Savings Growth Step by Step
- Using a Savings Calculator With Monthly Contributions
- What a Compound Interest Savings Calculator Shows You
- Reverse the Math With a Savings Goal Calculator
- Run Your Own Numbers in the 2026 Calculator
- Frequently Asked Questions
How a Savings Growth Calculator Turns Deposits Into Projections
The core idea is simple. You put money in. The bank pays interest. That interest earns interest too.
But here's what most guides get wrong: they show you a big final number and skip the assumptions behind it. Those assumptions decide everything.
Below, we'll show you exactly how to use an easy savings growth calculator in 2026, what each input actually does, and how to read the output without fooling yourself.
The Inputs You Need Before You Start
Five numbers drive every projection. Get these right and the output means something.
- Starting balance: what you have in the account today.
- Regular contributions: how much you add, and how often.
- Annual interest rate or APY: the rate the account pays.
Miss one and the estimate drifts. A common mistake is entering the rate as a decimal when the tool wants a percentage. Check the field label before you type.
How to Calculate Savings Growth Step by Step
Here is the manual method, so you understand what the tool does under the hood. The formula for compound growth with regular deposits is:
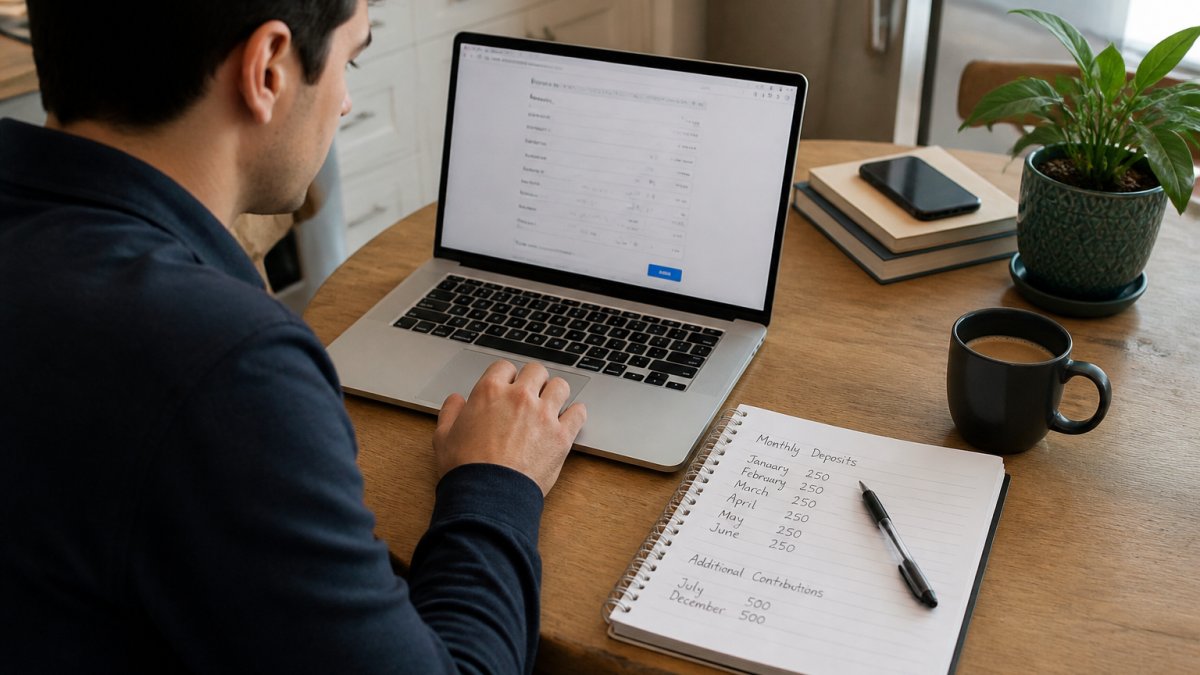
Future value = P × (1 + r/n)^(n×t) + PMT × [((1 + r/n)^(n×t) - 1) ÷ (r/n)]
Where P is your starting balance, r is the annual rate as a decimal, n is compounding periods per year, t is years, and PMT is your deposit per period.
That looks heavy. In practice, you do this:
- Write down your starting balance.
- Divide your annual rate by the compounding periods per year.
- Add 1 to that result.
- Raise it to the power of periods times years.
- Multiply by your starting balance.
- Add the future value of your regular deposits.
Most people stop at step 2 and reach for a calculator. That is the right call. But to trust the output, you should see one example worked end to end.
A Worked Example You Can Check
Assume a starting balance of $2,000, a monthly deposit of $200, an annual rate of 4.00% compounded monthly, and a 5-year horizon.
- Monthly rate: 0.04 ÷ 12 = 0.003333
- Number of periods: 12 × 5 = 60
- Growth factor: (1 + 0.003333)^60 ≈ 1.2209
Now split the total. You contributed $2,000 + ($200 × 60) = $14,000. Interest earned is roughly $1,695.80.
Run the same inputs with annual compounding instead of monthly and the projected balance drops by a small but measurable amount, because interest is added less often.
The Bankrate simple savings calculator is one reference point for how these projections are framed, and it lists an average APY of 0.59% as a baseline for estimating growth. That number matters: at a rate that low, deposits do most of the work, not interest. Run the worked example above at 0.59% and the interest line nearly disappears, a useful reality check before you assume a higher rate.
Using a Savings Calculator With Monthly Contributions
A savings calculator with monthly contributions shows how small, steady deposits compound over time. A free Roth IRA calculator lets you see how regular monthly contributions inside a Roth IRA would grow.
Monthly deposits beat annual lump sums for one reason: money added earlier has more time to earn. A deposit made in January compounds for eleven more months than one made in December.
What Deposit Frequency Changes
Frequency changes the total, and the gap widens with time. Here is how the same annual amount behaves under different schedules, using a $2,400 annual contribution, a 4.00% annual rate compounded monthly, and a 10-year horizon.
| Deposit Schedule | Money In Per Year | Compounding Chances | Approx. Projected Balance |
|---|---|---|---|
| Monthly ($200/mo) | $2,400 | 12 per year | ≈ $29,400 |
| Quarterly ($600/qtr) | $2,400 | 4 per year | ≈ $29,200 |
| Annually ($2,400/yr) | $2,400 | 1 per year | ≈ $28,800 |
The lesson: match your deposit frequency to your pay cycle. If you get paid twice a month, schedule two deposits. Automation removes the temptation to skip.
Scenario Planning: Three Contribution Strategies Side by Side
A single projection is a guess. Three projections side by side is a plan. Run the same starting balance and rate through three deposit levels and compare the contribution-versus-interest split at the end of the horizon.
Using a $2,000 starting balance, a 4.00% annual rate compounded monthly, and a 10-year horizon:
| Monthly Deposit | Total Contributed | Approx. Interest Earned | Approx. Final Balance |
|---|---|---|---|
| $100 | $14,000 | ≈ $2,700 | ≈ $16,700 |
| $200 | $26,000 | ≈ $5,400 | ≈ $31,400 |
| $400 | $50,000 | ≈ $10,800 | ≈ $60,800 |
Notice that doubling the deposit more than doubles the final balance, because the interest line grows too. That is the compounding effect in one table.
What a Compound Interest Savings Calculator Shows You
A compound interest savings calculator separates two numbers people constantly confuse: total contributions and interest earned. That split is the whole point.
Total contributions are the money you put in. Interest earned is what the account added. Early on, contributions dominate.
Keep in mind that a projection that shows a large interest figure over a long period is not a promise.
APY versus interest rate is the other trap. The nominal rate is the headline number.
Reverse the Math With a Savings Goal Calculator
A savings goal calculator works backward. You give it the goal amount and the target date, and it returns the deposit you need.
The method:
- Enter your goal amount.
- Enter your current balance.
- Set the target date.
Then stress-test it. Add a year to the timeline and watch the required deposit fall. Cut the timeline and watch it climb. That trade-off is the real decision.
A goal amount set today may buy less at the target date, so consider inflation when you choose a target. You can use a free inflation calculator to check how inflation affects the real value of your projected savings.
For longer horizons, consider connecting the goal to a retirement target.
Run Your Own Numbers in the 2026 Calculator
Reading about projections only gets you so far. The useful step is running your own figures.
Start with your real balance and your real deposit. Then change one input at a time and note how the projected balance moves.
Three things to check before you trust any output:
- Fees: a monthly account fee quietly cuts your real return.
- Taxes: interest in a taxable account is taxed, so your real return is lower than the projection.
- Variable rates: most savings rates are not locked. Model a lower rate to see the downside.
Capital Rewards offers a free savings growth calculator that runs these scenarios in real time without an account. It sits alongside other free calculators on the site.
Frequently Asked Questions
How do I calculate how much my savings will grow?
Enter four figures into a savings growth calculator: your starting balance, the amount you add each month, the annual percentage yield (APY) your account pays, and how many years you plan to save. The calculator compounds the balance and adds each deposit, then shows your projected balance, total contributions and interest earned. To check the result by hand, apply the periodic rate to the balance each compounding period, then add that period's deposit. Compare your own account's APY with other savings accounts before assuming a figure.
Does a savings calculator with monthly contributions include the deposits I make?
Yes. A savings calculator with monthly contributions adds each deposit to the balance before applying the next period's interest, which is why the result is higher than multiplying your monthly deposit by the number of months. The difference is the interest those deposits earn while they sit in the account. If you skip the contribution field, the calculator assumes a lump sum that never grows, and your projection will understate the final balance. Set the deposit frequency to match how often you actually transfer money, whether that is weekly, fortnightly or monthly.
How does compound interest affect savings over time?
Compound interest pays interest on your interest, so the balance accelerates the longer it stays invested. A compound interest savings calculator shows this as a widening gap between total contributions and total interest earned. Early in the timeline, most of the projected balance comes from what you deposit. In later years, interest makes up a larger share. That is why extending the time horizon by a few years often moves the final number more than raising the rate by a fraction of a percent. Compounding frequency matters too: daily compounding grows slightly faster than monthly compounding at the same stated APY.
What information do I need to use a savings goal calculator?
You need three things: the goal amount, the date you want to reach it, and the APY on the account you will use. A savings goal calculator then solves for the monthly deposit required. If the answer is higher than you can afford, adjust one of the three inputs: push the target date out, lower the goal amount, or find a higher-yield savings account. Keep the projection in today's money by subtracting expected inflation, because a balance that looks sufficient in 2036 may buy less than it does now. Re-run the numbers whenever your rate or income changes.
Saving well is less about finding a high rate and more about consistency and honest assumptions. Run your numbers, stress-test the rate, and check what inflation does to the result. Capital Rewards gives you free, real-time calculators with no account required, covering savings, loans, mortgages, and retirement in one place. Get started with Capital Rewards and see what your deposits could become.